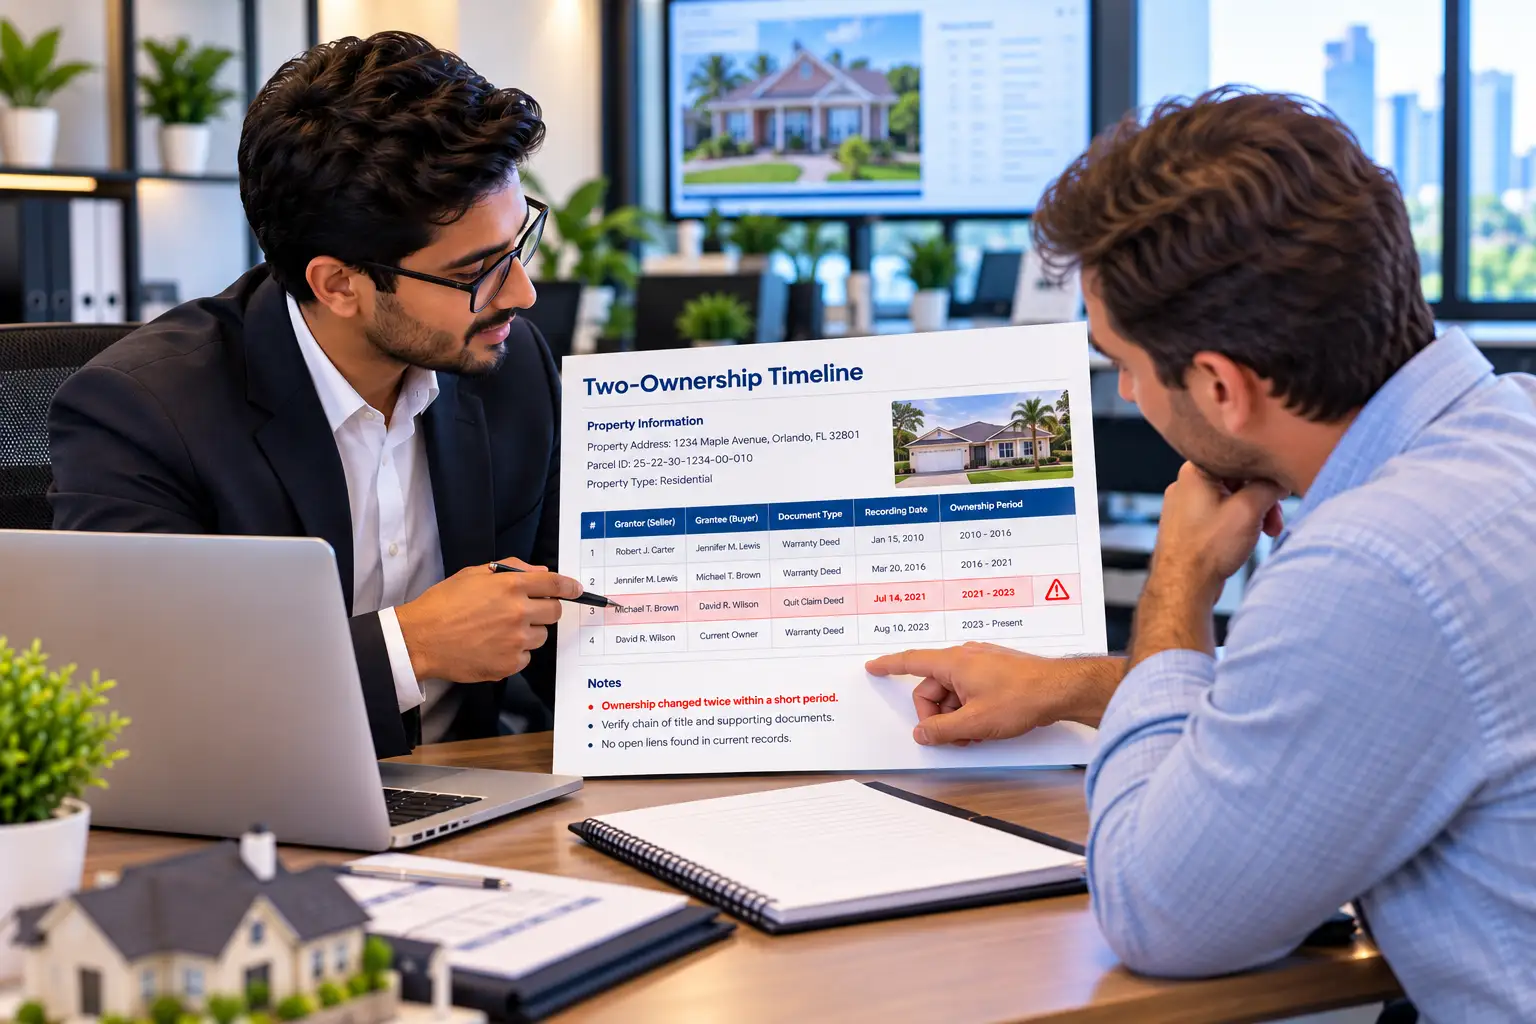
In real estate transactions, ordering the wrong title search usually leads to one of two outcomes: paying for unnecessary data that delays closing, or ordering too narrow a search and inheriting an unrecorded lien or cloud on title.
While a full 30- to 60-year statutory search is the gold standard for issuing brand-new title insurance on high-liability property purchases, most everyday refinances, investor acquisitions, HELOCs, and debt-recovery actions rely on limited searches.
The two most common choices are the Current Owner Search and the Two-Owner Search. Determining which search your deal requires depends on how each report functions, the risks involved, and the specific needs of the transaction.
What Is a Current Owner Title Search?
A Current Owner Search (often referred to as an Ownership & Encumbrance Report or O&E) examines public land records starting from the deed that transferred title to the present owner through the current date.
What it covers:
The deed conveying ownership to the current vested owner.
Real estate tax assessment status and delinquent property taxes.
Open mortgages and deeds of trust recorded against the property under the current owner.
Involuntary liens, mechanic’s liens, judgments, and lis pendens filed against the owner during their tenure.
Where it stops:
It treats the current deed as a fixed starting point. Everything recorded prior to the current owner taking title—including unreleased mortgages, liens against the prior owner, or defects in prior conveyances—is excluded from the scope.
What Is a Two-Owner Title Search?
A Two-Owner Search broadens the scope by stepping back to the transaction prior to the current owner. It traces the chain through two consecutive, arm’s-length transfers of ownership.
What it covers:
Everything in a Current Owner Search.
The prior owner’s vesting deed and the deed conveying the property to the current owner.
Open mortgages, unpaid balances, modifications, and assignments linked to the prior owner that were never formally released.
Judgments, state/federal tax liens, and municipal claims against both the prior and current owners.
Foreclosure documents or probate proceedings involved in the last transfer.
Key Comparison: Current Owner vs. Two-Owner Search
Factor | Current Owner Search (O&E) | Two-Owner Search |
Scope of Search | Current owner’s deed to present | Prior owner’s acquisition deed to present |
Average Turnaround | 4 to 24 hours | 24 to 48 hours |
Relative Cost | Lowest cost | Moderate |
Prior Mortgage Discovery | Misses unreleased prior mortgages | Captures open prior mortgages & assignments |
Deed Verification | 1 transfer event | 2 consecutive transfer events |
Primary Risk | "Zombie" liens and flawed prior conveyances | Doesn't capture issues predating the prior owner |
When Does a Current Owner Search Suffice?
Current Owner Searches are best suited for lower-risk transactions where existing title insurance remains active or the loan amount does not justify the expense of a deeper search:
Home Equity Lines of Credit (HELOCs) & Second Mortgages: Lenders often rely on current owner reports because the senior first lienholder already conducted a full title search at origination.
Standard Refinances with an Existing Policy: If the borrower purchased the property recently and has an active owner’s title policy, checking the gap between their deed date and today is often sufficient.
Preliminary Wholesaling & Off-Market Screening: Real estate investors screening tens of leads a week use O&E reports to quickly confirm ownership and verify that equity isn't wiped out by massive tax liens or first mortgages before writing an offer.
When Is a Two-Owner Search Required?
A Two-Owner Search is required when the validity of the previous transaction directly affects the safety of the current deal:
Properties Acquired via Quitclaim Deeds or Flips: If the current seller acquired the property only a few months ago, or through an intra-family quitclaim deed without title insurance, examining the prior owner’s record is vital to confirm valid consideration and legal transfer.
Foreclosure & Pre-Foreclosure Filings: Foreclosure attorneys must identify every party with an interest in the property to issue proper statutory notifications. If a prior mortgage was never properly subordinated or released, that lender remains a senior interest holder.
Auction & Tax Deed Acquisitions: When bidding at county sheriff sales or tax deed auctions, buyers typically purchase properties "as-is," subject to surviving liens. A Two-Owner Search flags unreleased mortgages, municipal assessments, or IRS tax liens attached to the previous owner that survive certain distressed actions.
Secondary Market & Private Lending Compliance: Non-QM lenders, private debt funds, and secondary mortgage buyers often mandate a two-owner chain to ensure the property hasn't been subject to illegal property flipping schemes or chain breaks.
The Real Danger: Unreleased Mortgages
The single greatest practical danger of defaulting to a Current Owner Search is the unreleased prior mortgage.
A Common Scenario: Owner A sells a home to Owner B. Owner A’s lender is paid off through escrow, but the closing agent fails to record the formal satisfaction/release of mortgage in county records.
A Current Owner search run on Owner B will only search records under Owner B’s name. It will miss that Owner A's mortgage is still active on the land records. If Owner B tries to sell or refinance, that cloud remains on title. A Two-Owner Search uncovers that defect immediately, allowing parties to track down a Certificate of Satisfaction before closing day.
Making the Decision
Choosing between these two reports comes down to risk tolerance and transaction type:
Choose a Current Owner Search if the current owner has held title for several years under a valid title policy, if you are originating a junior lien/HELOC, or if you simply need quick, low-cost confirmation of property taxes and recorded liens.
Upgrade to a Two-Owner Search if the current owner acquired the property recently, if you are purchasing through an auction or pre-foreclosure scenario, or if your lender/underwriter requires verification of the prior transfer to establish insurable, marketable title.